A leading environmental solution provider
Get in touch with usAuction volume: 10.8 million EUAs, 1.4 more than last week.
The fundamental backdrop for EUAs remains balanced, with policy uncertainty increasingly offsetting supportive energy market fundamentals. European gas storage has now reached 50%, reducing immediate concerns over security of supply and easing some of the weather-driven risk premium that dominated earlier in the year. At the same time, oil markets have become more stable after OPEC+ signaled higher production and shipping through the Strait of Hormuz remained uninterrupted, limiting broader upside pressure across the energy complex. Attention is now shifting back toward European climate policy. Reports that several European Commission departments have raised objections to the draft EU ETS reform, while the European Parliament has postponed discussions on changes to the Market Stability Reserve, introduce fresh uncertainty around the future supply of allowances. These developments may keep EUA prices volatile as the market reassesses whether future reforms will tighten or loosen the carbon market. Meanwhile, calls from the wind energy sector to reshape the ETS in favor of industrial electrification reinforce the longer-term structural demand case for carbon allowances, although any tangible impact is likely to materialize only over time. Geopolitical developments remain an important wildcard. Diplomatic efforts surrounding Ukraine continue, with renewed dialogue between Washington, Moscow and Kyiv potentially reducing some geopolitical risk premium if progress is made. However, Europe's second major heatwave of the summer presents a more immediate market driver. Exceptionally high temperatures are increasing electricity demand while putting pressure on French nuclear generation, potentially lifting gas-fired power production and, consequently, demand for EUAs.
The week ahead presents a mixed but constructive backdrop for EUAs. Softer oil and comfortable gas storage levels reduce some upward pressure, but policy uncertainty surrounding ETS reform and weather-driven increases in power demand could continue to support prices. As a result, EUAs may remain range-bound in the short term, with sentiment likely to be driven more by political developments and electricity market dynamics than by fuel markets alone.
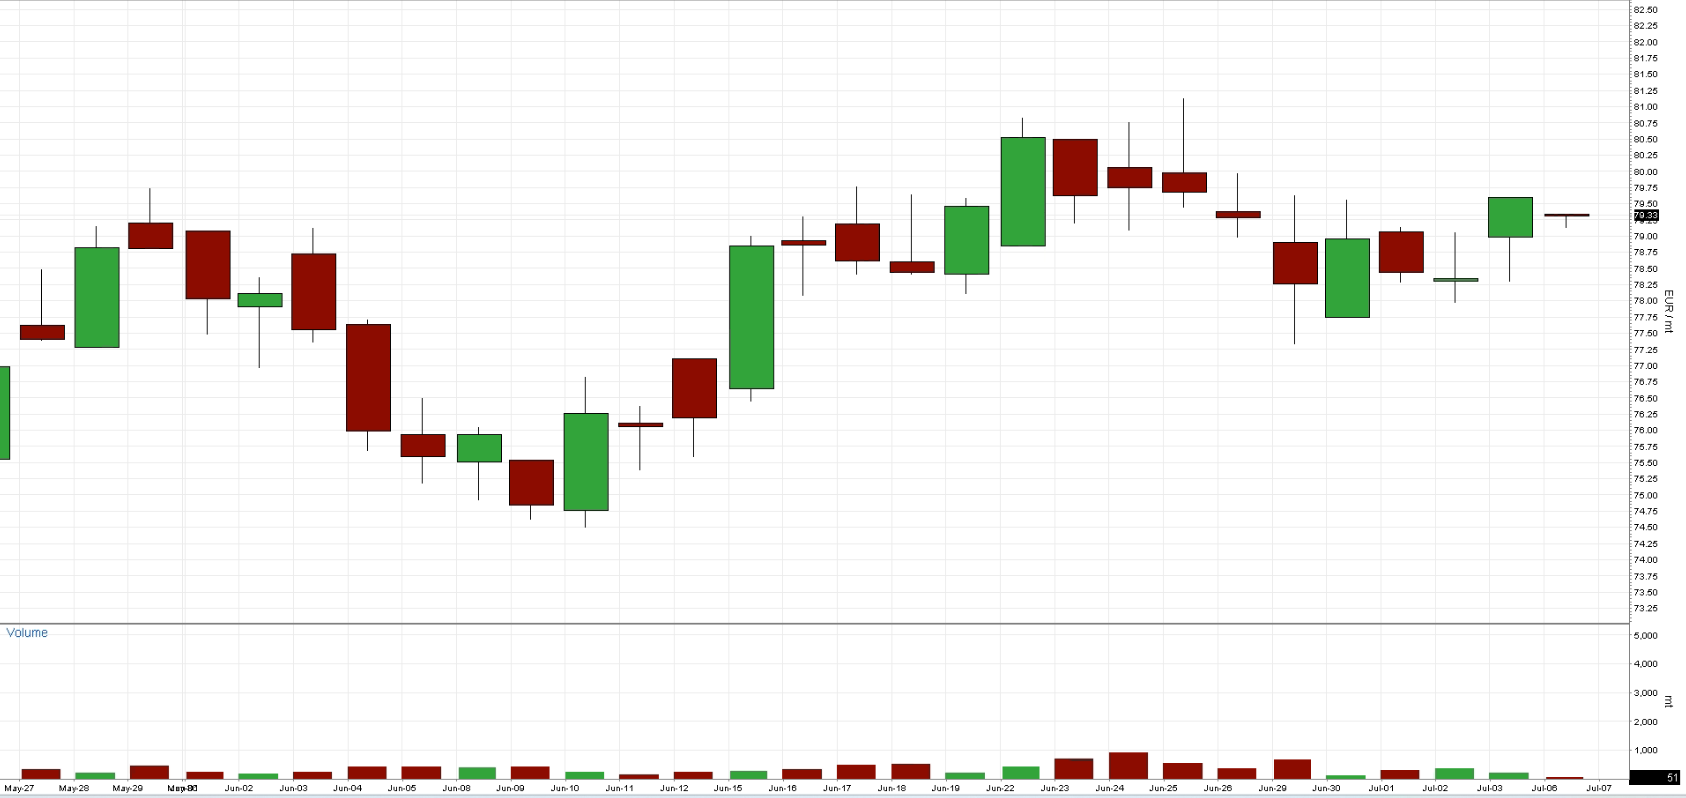
Chart A: EUA Spot (Futures Today) Price (EUR)
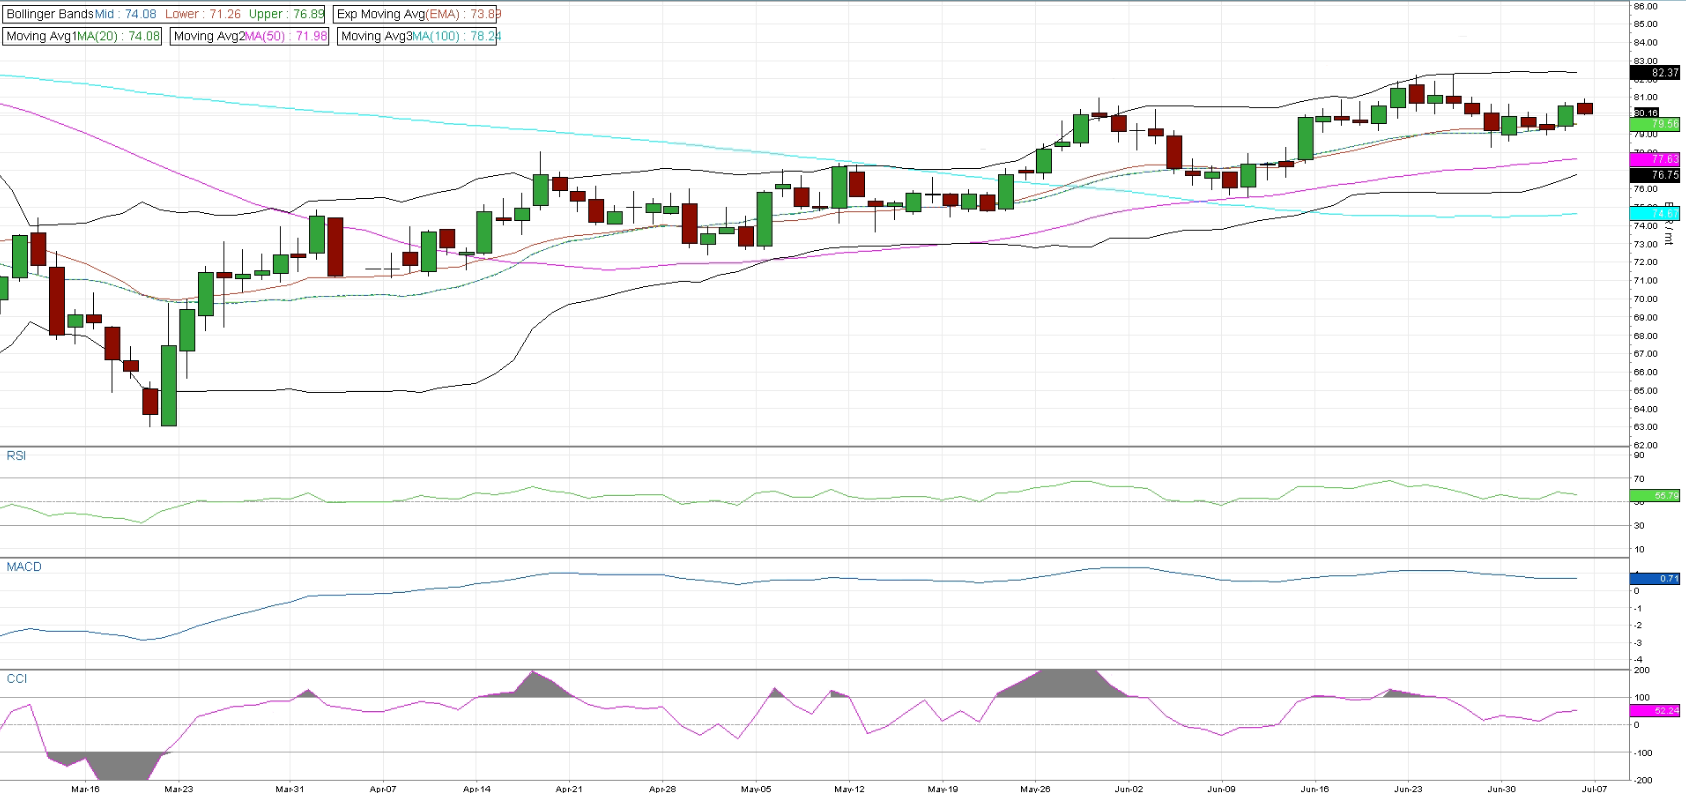
Price action continues to develop within a constructive recovery phase, characterized by a sequence of higher highs and higher lows since the March bottom. The market is comfortably trading above the 50-day MA (≈77) has turned higher and now acts as dynamic support. Although the 100-day MA (≈75) remains below, price has repeatedly tested this area, suggesting the longer-term downtrend is gradually losing influence. The Bollinger Bands remain moderately expanded, with price consolidating in the upper half of the range after its recent advance. Rather than showing signs of exhaustion, this behaviour points to healthy consolidation following the strong recovery. As long as price remains above the mid-band, the short-term technical structure continues to favour buyers. Momentum indicators also support the improving picture. RSI is holding around 56, reflecting steady bullish momentum without approaching overbought territory. CCI has recovered into positive territory, indicating renewed buying interest after the recent pullback, while MACD remains well above the zero line despite flattening slightly, suggesting upside momentum is moderating rather than reversing. The €80–82 region now represents the primary resistance zone, coinciding with recent swing highs and the vicinity of the moving averages. A decisive break above this area would strengthen the case for a continuation of the recovery. The technical backdrop has improved to moderately bullish. The series of higher highs and higher lows remains intact, moving averages are beginning to align positively, and momentum indicators continue to support the recovery. While resistance around €80–82 may temporarily cap further gains, holding above the short-term moving averages would tend to keep the constructive trend intact and leave room for further upside in the days ahead.
Chart B: December 2026 EUA Price (EUR) - Technical
AFS ENERGY B.V.
The information contained in the AFS Energy EU ETS Report, hereinafter Report, has been compiled or arrived from sources believed to be reliable but no representation or warranty, express or implied, is made as to their accuracy, completeness, timeliness, correct sequencing or correctness.
AFS Energy B.V. does not accept any liability, contingent otherwise for (i) the accuracy, completeness, timeliness or correctness of any information provided in the Report, (ii) any decision made, or action taken by you in reliance upon any of them and (iii) any direct or consequential loss arising from the use of the Report. AFS Energy B.V. does not make any representation or warranty about the suitability of the information in the Report.
The information contained in the Report is published for the assistance of the recipient but is not to be relied upon as authoritative or taken in substitution for the exercise of judgement by any recipient.